Costly Medicare mistakes you should avoid making (Part 2)
Published in Health & Fitness
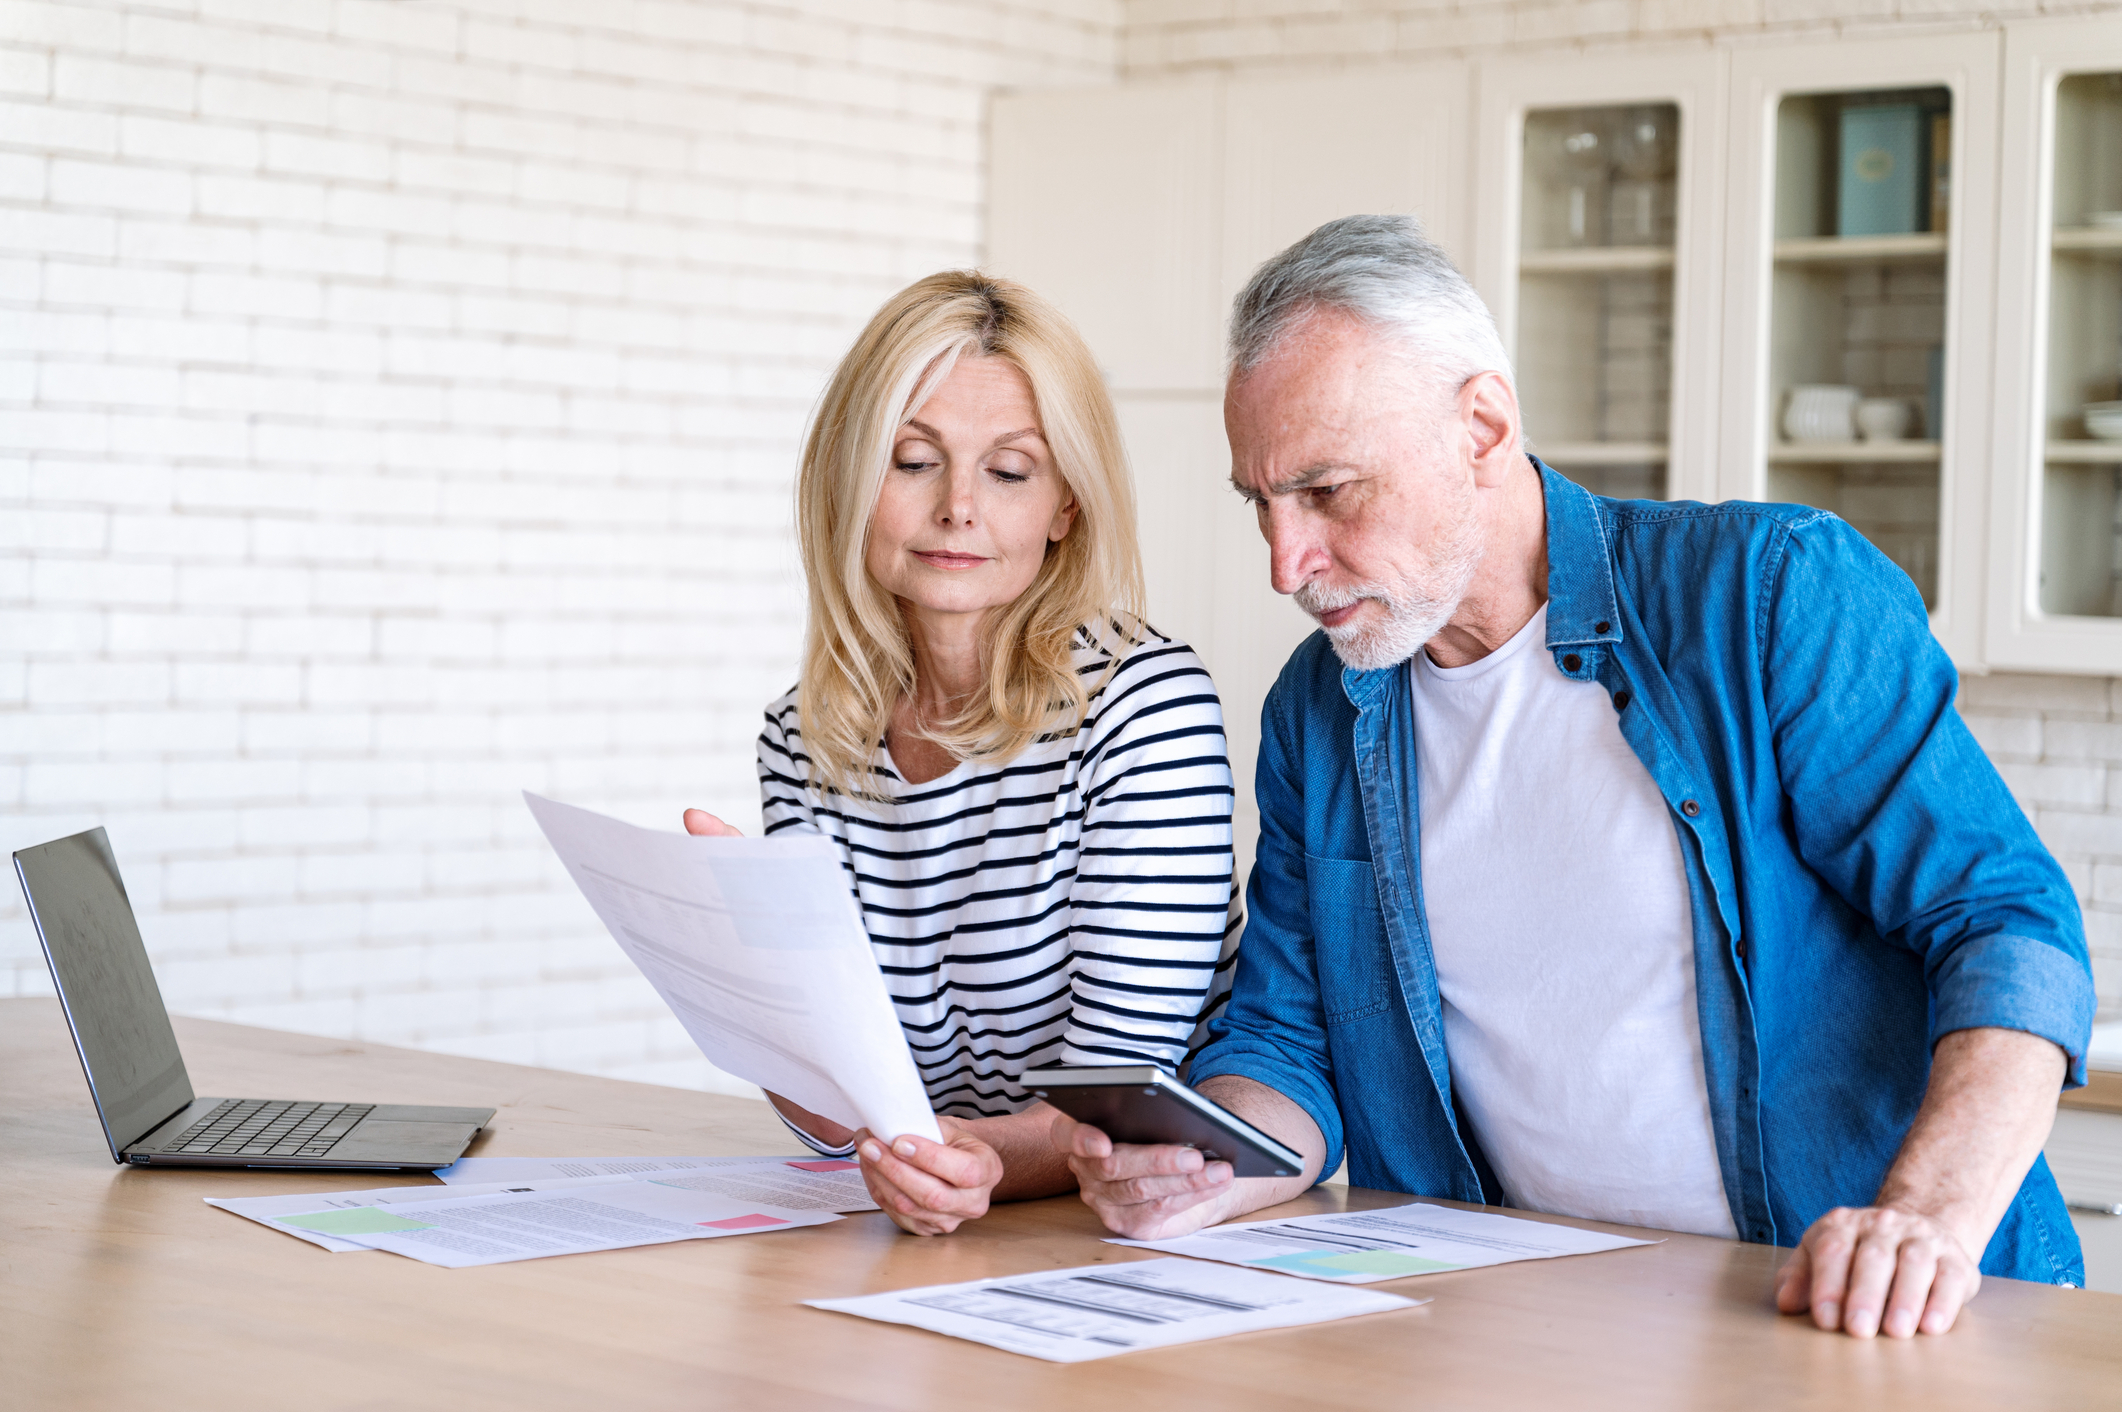
Medicare covers the bulk of your health care expenses after you turn 65. But Medicare’s rules can be confusing and mistakes are costly. If you don’t make the right choices to fill in the gaps, you could end up with high premiums and high out-of-pocket costs. Worse, if you miss key deadlines when signing up for Medicare, you could have a coverage gap, miss out on valuable tax breaks, or get stuck with a penalty for the rest of your life.
Here are six common Medicare mistakes you should avoid making:
1. Forgetting that you can sign up for Medicare at 65
If you’re already receiving Social Security benefits, you’ll automatically be enrolled in Medicare Part A and Part B when you turn 65. But if you aren’t receiving Social Security benefits, you’ll need to take action to sign up for Medicare.
Although you can turn down Part B coverage and sign up for it later, you can’t disenroll from Medicare Part A. As most people receive it premium-free, it can serve as secondary hospital insurance.
If you’re at least 64 years and 9 months old, you can sign up online. You have a seven-month window to sign up — from three months before your 65th birthday month to three months afterward.
You may want to delay signing up for Part B if you or your spouse has coverage through a current employer. And if you want to continue to contribute to a health savings account, you may want to delay signing up for Medicare Part A. You can’t be enrolled in Medicare and contribute to an HSA. You also have to be careful about running afoul of the six-month lookback rule applied to HSA contributions when you finally decide to sign up for Medicare.
See the Social Security Administration’s Applying for Medicare Only for more information. If you work for an employer with fewer than 20 employees, you must sign up for Part A and usually need to sign up for Part B, which will become your primary insurance (ask your employer whether you can delay signing up for Part B).
2. Not signing up for Medicare Part B if you have retiree or COBRA coverage
When you turn 65, Medicare is generally considered to be your primary insurance, and any other coverage you have is secondary, unless you or your spouse has insurance through a current employer with 20 or more employees.
But the coverage must be with a current employer. Other employer-related coverage, such as retiree coverage, COBRA coverage, or severance benefits, isn’t considered to be primary coverage after you turn 65.
That means if you don’t sign up for Medicare, you may have gaps in coverage and be subject to a l ifetime late-enrollment penalty of 10% of the current Part B premium for every year you should have been enrolled in Part B but were not.
3. Forgetting about the Medicare Part B enrollment deadline after leaving your job
When you have coverage through an employer with 20 or more employees, you don’t have to sign up for Medicare at 65. But you need to sign up within eight months after you leave your job, or you may have gaps in your coverage. You may have to wait until the next enrollment period, and you may also get hit with the 10% lifetime late-enrollment penalty
You qualify for a special enrollment period (SEP) and will not be liable for penalties when you enroll within the 8-month window. You can sign up for Medicare within 8 months of the day you or your spouse stops working, even if your group health plan continues for a time. Or you can sign up within 8 months of your group health plan ending, even while you or your spouse continues to work. Coverage typically begins the month after you sign up.
4. Making financial moves that increase your Medicare premiums
Most people pay the standard premium for Medicare Part B. For 2026, that is $202.90 per month. But if you’re a high-income earner, you will pay the income-related monthly adjustment amount (IRMAA) for Part B.
For 2026, those who were single with an adjusted gross income from 2024 of more than $109,000 (or more than $218,000 for joint filers) pay an additional monthly surcharge. This surcharge ranges from $81.00 to $443.90 in 2026.
And you’ll have to pay a high-income surcharge for your Part D prescription drug coverage, too, which can boost your premiums by $14.50 to $91.00 per month in 2026.
This surcharge is assessed by the Social Security Administration (SSA) based on your income from two years prior. Income from your 2024 tax return was used to determine your liability for 2026. For 2027, the SSA will use the information on your 2025 tax return.
If you’re near the income cutoff, be careful about financial moves that could increase your adjusted gross income and make you subject to the surcharge, such as rolling over a traditional IRA to a Roth IRA or making big withdrawals from tax-deferred retirement accounts. To stay below the limits, you may want to spread your Roth conversions over several years. Read 7 Ways to Plan Now to Save on Medicare IRMAA Surcharges Later for ways to avoid and/or reduce your liability for the IRMAA.
5. Not contesting the high-income surcharge for the year you retire
Your Part B and Part D premiums will be higher if your income is over a certain threshold. The Social Security Administration (SSA) uses your most recent tax return on file (which will be your 2025 for 2027 premiums) to determine whether you’re subject to the surcharge. For 2026, single filers with an adjusted gross income of more than $109,000 ($218,000 for joint filers) in 2024 pay more than the standard premiums.
But you may be able to get the surcharge reduced on appeal if your income has dropped since then because of certain life-changing events, such as marriage, divorce, death of a spouse, retirement, or a reduction in work hours. Be prepared to provide evidence of the life-changing event, such as a signed statement from your employer that you retired or proof of reduced income.
If the SSA is using a tax return from the wrong year, or you amended your tax return, you should contact the SSA. You can request they use a more recent year’s income (or amended return) to determine your IRMAA liability. In the case of an amended return, be prepared to share a copy with the SSA.
Read How to Appeal the IRMAA for Medicare Parts B and D and see the Social Security Administration’s Medicare Premiums: Rules for Higher-Income Beneficiaries for more information.
6. Signing up for Medicare Part A if you want to contribute to an HSA
If you or your spouse has health insurance through your current job, you can delay signing up for Part A and Part B and keep contributing to an HSA. This isn’t an option if you have already signed up for Social Security or your employer has fewer than 20 employees — in that case, you can’t delay signing up for Part A.
Be careful about your contributions in the year you leave your job and sign up for Medicare — you must prorate your HSA contributions based on the number of months prior to your Medicare coverage beginning.
And don’t forget that after you turn 65, you can use HSA money tax-free to pay premiums for Medicare Parts B and D and Medicare Advantage plans (but not premiums for Medicare supplement policies), in addition to paying for other out-of-pocket medical expenses.
(Donna LeValley is a retirement writer for Kiplinger.com.)
©2026 The Kiplinger Washington Editors, Inc. All rights reserved. Distributed by Tribune Content Agency, LLC.
Comments